

Dental Insurance Quotes: What to Compare Before You Choose
A dental insurance quote is an estimate of what you may pay for coverage based on a plan’s pricing and benefits. When comparing dental insurance quotes, it helps to look beyond the monthly premium, because two plans with similar prices can offer very different value depending on what care is covered and how costs are shared.
This article focuses on how to review quotes with preventive and periodontal care in mind. That includes checking whether routine services like dental cleaning are covered, how deep cleaning dental treatment is handled, and whether waiting periods apply before certain benefits begin. Premiums matter, but they are only one part of the decision.
To judge a quote accurately, compare annual maximums, deductibles, provider networks, coinsurance levels, and any limits on specific procedures. A plan that looks affordable at first glance may lead to higher out-of-pocket costs later if coverage is restricted. The right choice depends on your expected care needs, benefit details, and overall budget.
Why similar quotes can lead to very different out-of-pocket costs
Monthly premium is only one cost factor. Your deductible, the plan’s annual maximum, and the percentage paid for covered procedures can all change what you actually spend. If one quote covers preventive care generously but offers limited support for periodontal treatment, it may be less valuable for someone who expects more than routine visits. Reviewing the full benefit structure makes quote comparisons more useful and realistic.
What a Dental Insurance Quote Usually Includes
A dental insurance quote usually gives you a snapshot of a plan’s price and structure so you can compare options more confidently. In plain terms, it shows what you may pay each month, what cost-sharing rules apply, and how different types of dental care are often covered. It is helpful for comparison, but it is still an estimate, not a guarantee of exact out-of-pocket costs for every procedure.
Key terms to know before comparing plans
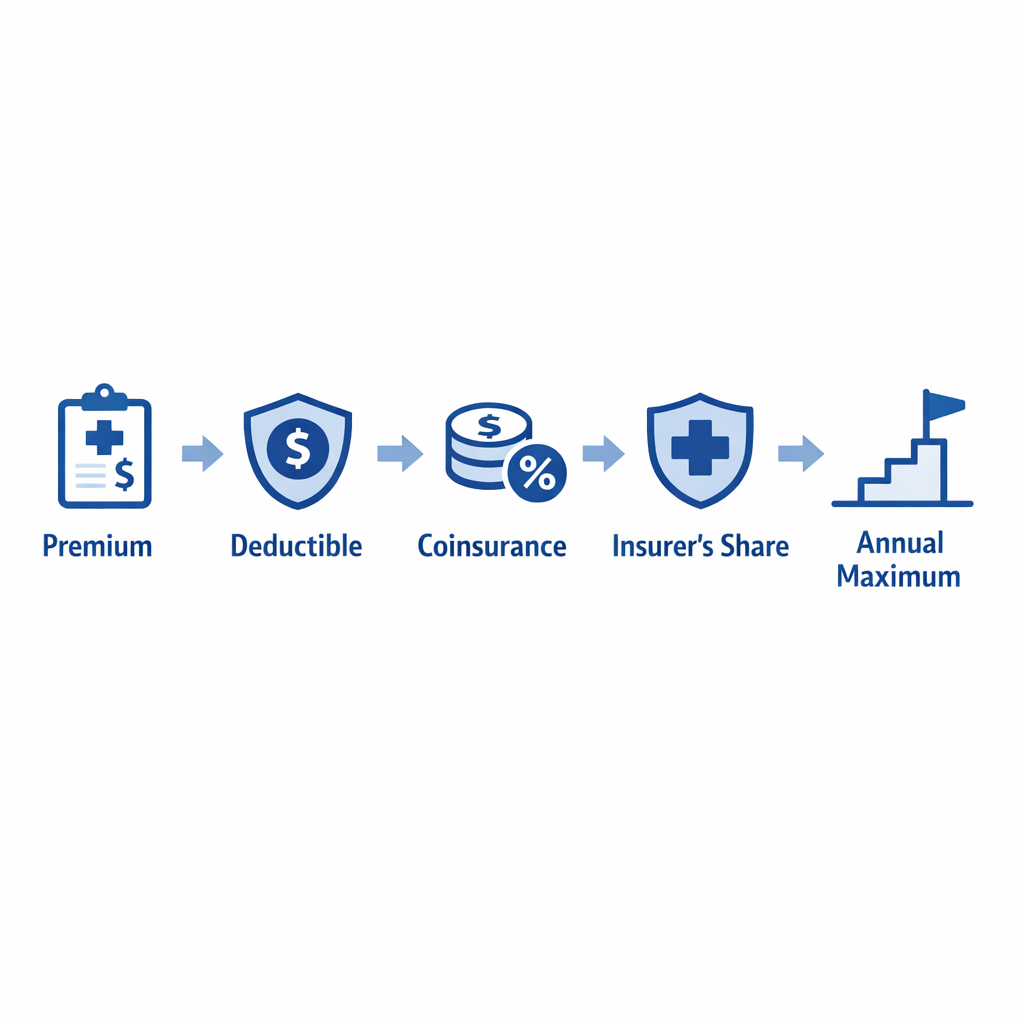
Premium is the monthly amount you pay to keep the plan active. A deductible is the amount you may need to pay before certain services begin receiving plan benefits. The annual maximum is the most the plan may pay toward covered dental care in a plan year. Coinsurance is the percentage of a bill you share after plan rules apply, while a copay is a set dollar amount for certain services. A waiting period means some treatments may not be covered right away. Network refers to the dentists who have agreed to the insurer’s pricing, which can affect your total costs.
How insurers group dental services
Many dental plans group care into preventive, basic, and major services. Preventive care often includes exams, cleanings, and X-rays. Basic services may include fillings or simple extractions. Major services can include crowns, bridges, dentures, or root canals, depending on the plan. These categories matter because each one may have different coverage levels, waiting periods, or cost-sharing rules. Category placement can also vary by insurer and plan, so reading the summary carefully is important when comparing dental insurance quotes.
When you review a quote, think of it as a planning tool. It helps you understand how a plan is designed, but actual costs can still depend on the dentist you choose, the treatment you need, and the final benefit determination.

Why Comparing Quotes Carefully Can Save Money and Frustration
Comparing dental insurance quotes carefully can help people look past the monthly premium and focus on overall value. A lower premium may seem appealing at first, but plan details can make a meaningful difference in what you actually pay over time. Depending on the policy, a lower-cost option may come with a higher deductible, a lower annual maximum, a narrower network, or a longer waiting period before certain services are covered.
Why the cheapest premium is not always the best value
When reviewing plan comparison details, it may help to ask what happens after the premium is paid. If a plan has a low annual maximum, even routine and follow-up care can use benefits faster than expected. If the network is limited, out-of-pocket costs may also be higher. For some people, paying a bit more each month can mean more predictable access to care, but the right choice depends on plan terms and personal priorities.
How future dental needs affect quote selection
Quote comparison may be especially useful for people planning regular dental cleanings, periodontal maintenance, or other ongoing visits. Those considering future specialty treatment should also review major-service coverage carefully, including waiting periods, coinsurance, and annual limits. Looking ahead can reduce surprises and support better decision-making. In some cases, reviewing advanced periodontal therapy options overview may also help people think through how treatment needs and benefit design can connect.
A balanced comparison is not about finding a universally best plan. It is about choosing coverage that may fit expected care, budget, and comfort with out-of-pocket risk.

The Most Important Factors to Compare in Dental Insurance Plans
When reviewing dental insurance quotes, it helps to use the same checklist for every option so you can compare value instead of just price. A lower monthly premium may look appealing at first, but the real question is how the plan handles deductibles, annual maximums, waiting periods, network rules, reimbursement levels, missing tooth clauses, and exclusions. If you are comparing plans for routine care, major treatment, or even dental insurance for braces, a structured side-by-side review can make the differences much clearer.
Use the framework below to evaluate each quote carefully, and always confirm details in the policy documents before assuming a specific service will be covered.
Premiums, deductibles, and annual maximums
Start with the three numbers that most directly affect yearly cost. The premium is what you pay each month to keep the plan active. The deductible is the amount you may need to pay before certain benefits begin. The annual maximum is the total amount the plan may pay in a benefit year. A plan with a low premium but a low annual maximum may offer less practical value than a plan with a slightly higher premium and stronger benefits. Compare these numbers together rather than in isolation.
Waiting periods, exclusions, and limitations
Many plans place waiting periods on basic or major services, and some include exclusions or limitations that can significantly affect care. Look closely at reimbursement percentages for preventive, basic, and major treatment categories. Also check for missing tooth clauses, frequency limits, and any restrictions tied to specialty services. Orthodontic benefits, including dental insurance for braces, are often separate, capped, limited to certain ages, or not included at all in many adult plans. Details vary by insurer and policy, so verification matters.
Network rules and provider access
Provider rules can affect both cost and convenience. PPO plans may offer more flexibility but different reimbursement levels for in-network versus out-of-network care. HMO-style plans may require a narrower provider network and more structured referrals. Before choosing a plan, confirm whether your preferred dentist or specialist participates and how out-of-network claims are handled. This step can be especially important if you expect complex treatment and want to plan ahead for costs, including topics such as financing options for dental implants.
Coverage for preventive and periodontal services
Do not assume all cleanings are treated the same. One plan may cover routine dental cleaning at a higher level, while another may apply different rules to periodontal maintenance or deep cleaning dental services. Review frequency limits, category definitions, and any notes about medical necessity or prior authorization. If periodontal care is important to you, compare how each quote describes preventive services, therapeutic cleanings, and related follow-up care.
Quick comparison checklist:
- Monthly premium
- Deductible amount
- Annual maximum
- Waiting periods
- Network and out-of-network rules
- Reimbursement percentages by service type
- Missing tooth clauses
- Exclusions and frequency limitations
- Coverage language for routine cleanings, periodontal maintenance, and deep cleaning dental services

Comparing Common Plan Types and Coverage Scenarios
When comparing dental coverage, it often helps to look at broad plan structures first, then narrow choices based on how you actually use care. Some options may be better for people who want provider flexibility, while others may suit those focused on lower monthly costs and routine in-network visits. The right fit depends on your budget, how often you go to a dental clinic, and whether you expect to need more specialized treatment.
PPO vs HMO vs indemnity-style plans
PPO plans often work for people who want a wider choice of dentists and some out-of-network flexibility, though premiums and out-of-pocket costs may be higher. HMO-style plans may suit people comfortable choosing from a smaller network and following referral rules in exchange for more predictable costs. Indemnity-style plans are sometimes better for those who value provider choice most, but they may involve more paperwork and less cost control. Discount-style arrangements are different from insurance and may simply reduce fees at participating offices rather than pay claims toward covered services.
What to know about braces and specialty coverage
Dental insurance for braces can be more limited than preventive or basic restorative coverage. Orthodontic benefits may have age restrictions, waiting periods, separate deductibles, or lifetime maximums that cap what the plan will pay. Specialty care can also follow different rules depending on the policy, so it is important to review exclusions and preauthorization requirements carefully. If you are also comparing larger restorative needs, this dental implant treatment options guide may help you understand how treatment type can affect planning and expected costs.
For many people, preventive coverage and network flexibility are the main priorities, especially if they schedule regular cleanings and exams. Others may focus more on potential support for braces or other specialized services. Comparing plan rules side by side usually gives a clearer picture than looking at premiums alone.
Looking Beyond the Quote: Real-World Costs to Estimate
When comparing dental coverage, it helps to look past the monthly premium and think in terms of total yearly spending. A lower premium may seem attractive at first, but the real value of a plan often depends on how deductibles, coinsurance, copays, and annual maximums work together once you actually use care.
A practical way to budget is to start with the premium you expect to pay over 12 months. Then add the costs you may reasonably face for preventive visits, standard exams, cleanings, and any likely follow-up treatment. If you already know you may need periodontal maintenance or additional visits, include those in your estimate as well. This gives you a more realistic picture than comparing quotes alone.
How to estimate your likely yearly dental spending
Think of the math in layers: annual premium, then deductible, then your share of covered services through coinsurance or copays, all while keeping the plan’s annual maximum in mind. Once benefits are used up, you may be responsible for a larger share of treatment costs. That is why utilization matters so much when judging whether a plan fits your needs.
Because exact out-of-pocket costs depend on plan terms, provider fees, and individual treatment needs, estimates should stay general until you review the details carefully. If you are also weighing long-term cost considerations in dentistry, it can be helpful to compare likely yearly spending scenarios rather than focusing on one quoted number.
How to Review Dental Insurance Quotes Step by Step
Use this simple checklist to compare quotes in a practical way and narrow your options with more confidence. The goal is not to predict every cost, but to make sure the plan matches your likely care needs, timing, and provider preferences.
A simple 5-step quote review checklist
- List your likely care needs for the year. Think about cleanings, exams, fillings, crowns, gum care, or any treatment you may already expect. This gives you a practical baseline for comparing benefits.
- Compare annual maximums and waiting periods. A lower premium may come with stricter limits or delays before certain services are covered, so review both numbers together.
- Verify network participation and exclusions. Check whether your preferred dentist or specialist is in network and look closely at services the plan does not cover.
- Review preventive and periodontal coverage details. Confirm how often preventive visits are included and whether gum-related treatment has different limits, percentages, or conditions.
- Confirm anything unclear directly with the insurer or provider office. If a quote seems vague, ask for clarification before enrolling. If you are also researching treatment timing, this same-day dental implant treatment overview may help you frame questions about future care needs.

Questions to Ask If You Expect Ongoing Gum Care
If you think you may need ongoing gum-related care, it can help to review your dental benefits before treatment planning begins. Coverage for periodontal maintenance, deep cleaning dental services, specialist visits, and follow-up appointments may vary, and the details often depend on your specific condition and your individual plan.
Benefit questions worth asking before treatment planning
Useful questions include: How often is periodontal maintenance covered? Is there a waiting period? Are specialist evaluations included? Does your plan require preauthorization for certain services? You can also ask whether follow-up care is handled differently from routine cleanings and whether annual maximums may affect timing.
For the most accurate guidance, bring your insurance details to an in-person evaluation so the office can help you understand how your benefits may apply to your care needs. If you are also comparing restorative options connected to long-term oral health planning, you can review implant-supported tooth replacement options.
Frequently Asked Questions About Dental Insurance Quotes
Are dental insurance quotes accurate?
Dental insurance quotes are usually helpful estimates, but they are not a guarantee of final costs. Actual pricing and coverage can depend on plan terms, provider network participation, waiting periods, and the specific treatment you receive. It is best to confirm details before care is scheduled.
What should I compare besides the monthly premium?
Look beyond the premium and compare the deductible, annual maximum, waiting periods, network requirements, and exclusions. These details can affect how much you pay when you actually use the plan. A lower premium does not always mean lower overall costs.
Does dental insurance usually cover braces?
Some dental plans include orthodontic benefits, but braces coverage is often limited. Plans may have age restrictions, waiting periods, or lifetime maximums for orthodontic care. Review the policy carefully to see whether braces are included and under what conditions.
Are dental cleaning and deep cleaning dental services covered the same way?
Not usually. Routine cleanings are commonly treated as preventive care, while deep cleanings are often classified as periodontal or restorative treatment with different coverage rules. Because categories vary by plan, verify benefits before treatment.
Can I use dental insurance with a specialist?
In many cases, yes, but it depends on the plan’s network and referral rules. Some plans provide better benefits for in-network specialists, while others may require a referral from a general dentist. Check the benefit structure in advance so you understand your expected out-of-pocket costs.
When to Speak With a Periodontal Office About Your Benefits
If you have questions about how your dental benefits may relate to periodontal maintenance or specialty care, a periodontal office can help review the information you bring and discuss how benefits may apply to recommended care after an in-person evaluation. This can be a helpful next step when you want clearer guidance for treatment planning without making assumptions about coverage.
Bring your questions and plan details to your visit
Bring your plan details, treatment history, and any questions you want to discuss. A personalized conversation can help you understand the recommended care, what information may be needed for insurance verification, and what to ask before moving forward.
Choose Dental Insurance Quotes With More Confidence
When comparing dental insurance quotes, the best option is not always the lowest monthly price. The right plan depends on the care you expect to need, what fits your budget, how long you may need to wait for certain services, and exactly what the policy covers once treatment begins.
As you review quotes, focus on total value rather than headline cost alone. Check deductibles, annual maximums, exclusions, and whether preventive services are covered as expected. If gum health is a concern, it is especially important to verify periodontal benefits carefully so you understand what is included before scheduling care.
Focus on value, not just the quote price
A confident decision comes from comparing details side by side and choosing a plan that matches your likely needs. With a clear framework and a careful review of coverage terms, you can move forward knowing your quote supports informed, practical decision-making.
Recent Comments